How a Wind Mitigation Inspection Can Save You Hundreds on Florida Insurance
Florida homeowners pay some of the highest insurance premiums in the country. A wind mitigation inspection is one of the fastest ways to lower your costs. Here is how it works.
Why Florida Insurance Is So Expensive
Hurricanes drive everything. After several active storm seasons, insurers raised rates sharply, tightened underwriting, and in some cases left the state entirely. For homeowners, that means higher premiums and more paperwork. But Florida law also gives you a powerful tool: insurers must offer discounts for verified wind-resistant features. The catch is that the features have to be documented on the state's official form, and that is exactly what a wind mitigation inspection does.
The Features That Earn You Credits
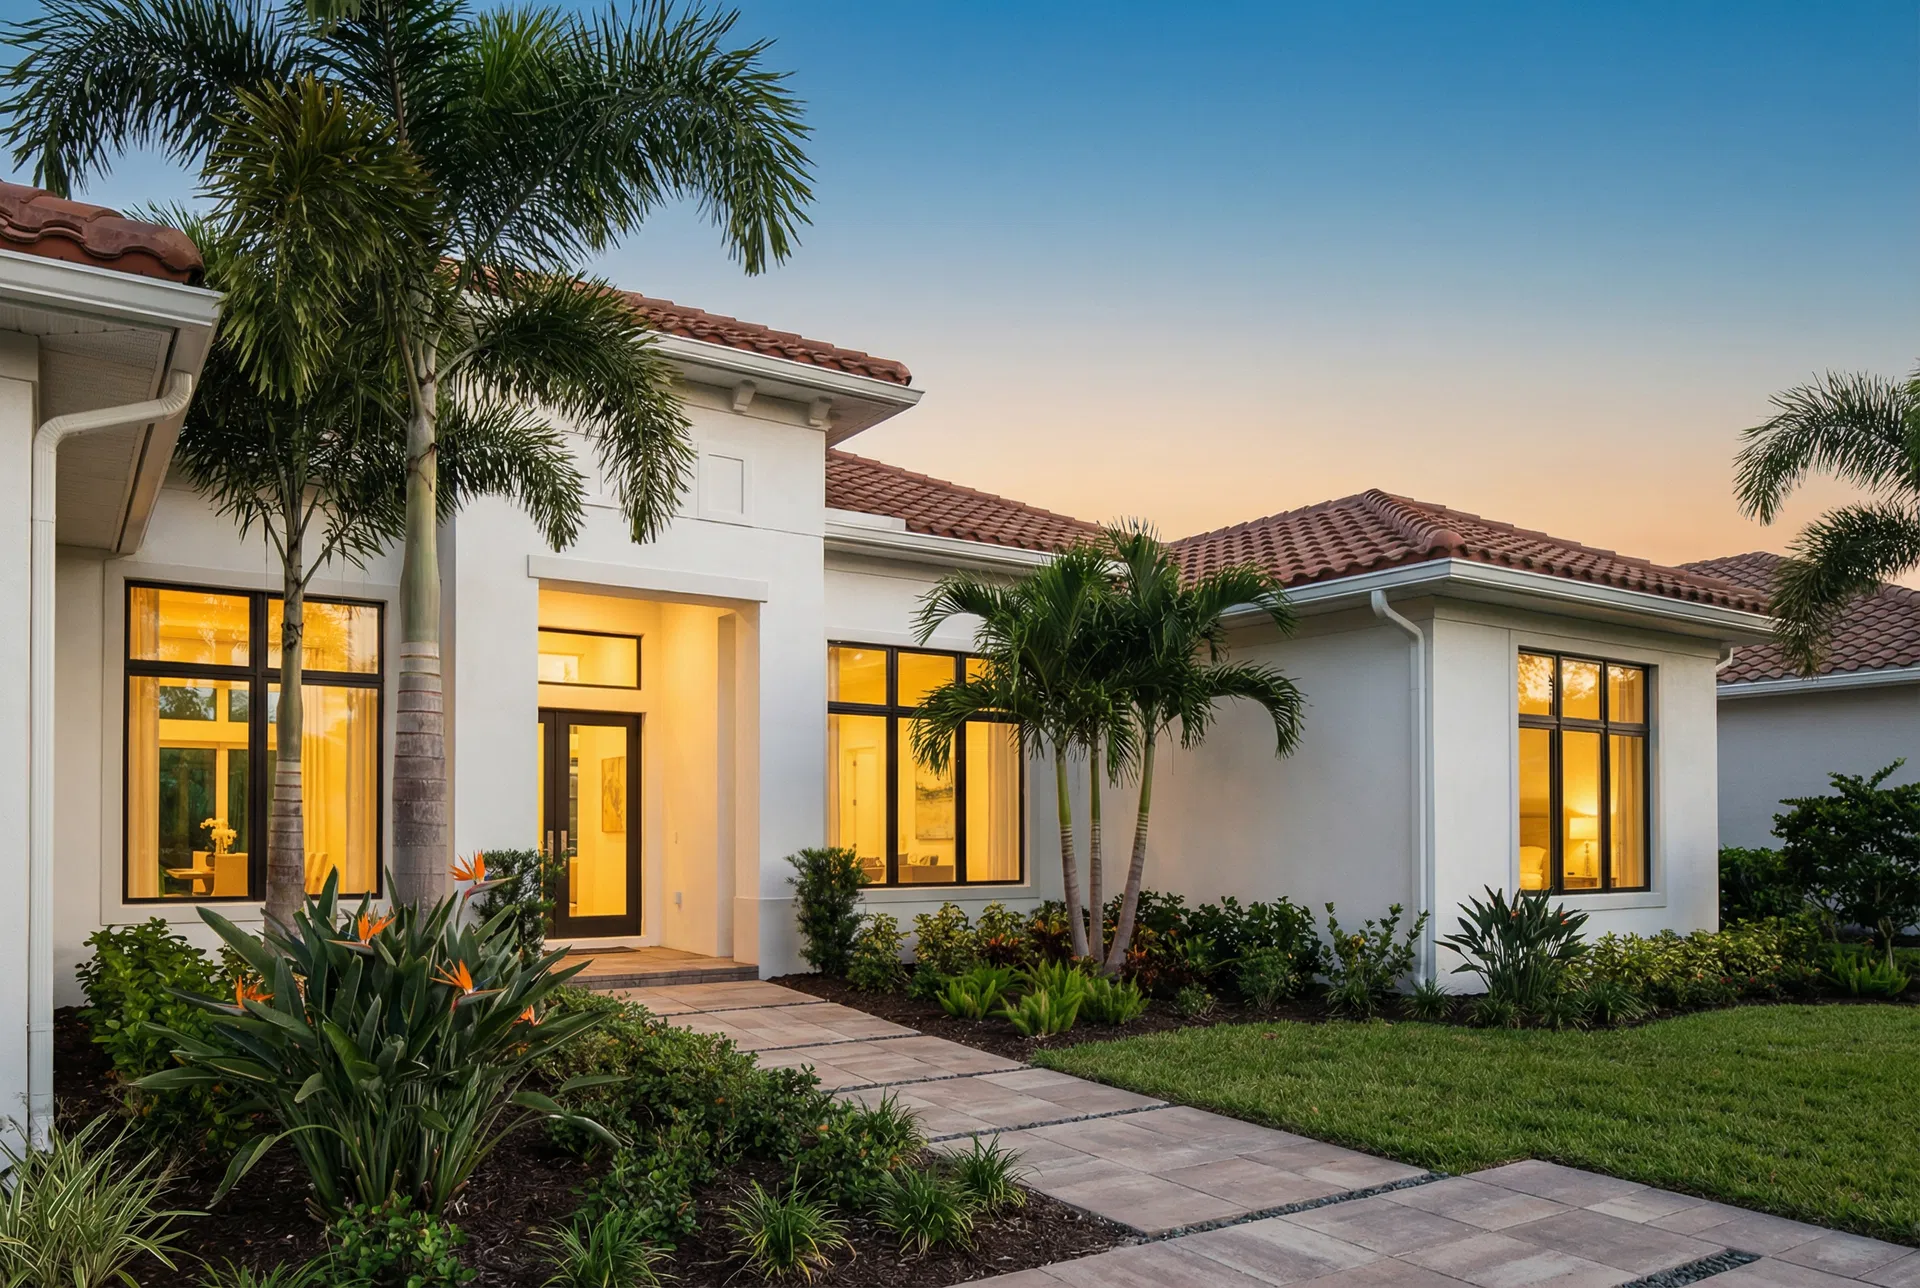
The OIR-B1-1802 form documents seven categories. Roof shape matters: hip roofs, which slope on all four sides, earn stronger credits than gable roofs. Roof-to-wall connections are next: hurricane clips and single or double wraps score far better than simple toe nails. The form also records how the roof deck is attached, the age and type of the roof covering, whether a secondary water barrier protects against intrusion, and what protects your openings, meaning impact-rated windows and doors, shutters, or reinforced garage doors.
Each verified feature stacks credits on the windstorm portion of your premium. A newer home built to the modern Florida Building Code with impact glass throughout can see dramatic savings. Even older homes often qualify for partial credits that add up to hundreds per year.
The Math: Cost vs. Savings
A wind mitigation inspection is one of the highest-ROI purchases a Florida homeowner can make. The inspection itself takes under an hour and costs a fraction of a single year's savings for most homes. The resulting 1802 form is generally accepted by insurers for five years, which means the savings compound year after year. If you have installed a new roof, added shutters, or upgraded to impact windows since your last inspection, get a new one: your credits should reflect your current home, not your old one.
How to Use Your Report
We deliver your completed, photo-documented 1802 form the same day by email. Send it to your insurance agent and ask them to apply every credit it documents. If you are shopping for a new policy, get quotes with the form in hand so carriers price your actual home instead of guessing. And if you are buying, ask the seller whether a current 1802 exists: it tells you what the home already earns before you ever call an agent.
Ready to schedule your inspection?
Get the clarity you need before you buy. Same-day reports, no surprises.
Ready to Inspect with Confidence?
Schedule your inspection today and get the clarity you need to make the right decision. Same-day reports, no surprises.